![special-case-sl-logo.png]](https://help.seedlegals.com/hs-fs/hubfs/special-case-sl-logo.png?width=165&height=18&name=special-case-sl-logo.png)
Using your last funding round's price per share for EMI options: What you need to know
When setting up an Enterprise Management Incentive (EMI) Option Scheme, one of the key decisions you'll need to make is the exercise price your employees will pay to acquire their shares.
You may be considering using the price per share (PPS) from your most recent funding round. While this is an option, there are some important considerations to bear in mind before proceeding.
At SeedLegals, we generally recommend obtaining an EMI valuation agreed with HMRC, as this can help you set a more favourable exercise price for your employees while providing greater certainty around the tax treatment of their options.
Let's explore why this matters and how to get started.
Why might using your last funding round's PPS not be the best approach?
1. It may reduce the incentive for your employees
One of the main purposes of offering share options is to reward employees for their contribution to the company's growth, often referred to as sweat equity.
Unlike investors, who contribute capital in exchange for shares, employees contribute their time, skills and expertise to help build the business.
By using the same PPS that investors paid in your last funding round, employees may be required to pay a relatively high amount to exercise their options.
This can make the options less financially attractive and reduce their effectiveness as a long-term incentive.
2. Exercising options could become expensive
It's worth considering how much your employees would actually need to pay when exercising their options.
For example:
Imagine your most recent funding round had a PPS of £5.00 and you granted an employee 2,000 options.
- Exercise price per option: £5.00
- Number of options granted: 2,000
- Total cost to exercise: £10,000
This means your employee would need to pay £10,000 to acquire their shares.
Although they may ultimately receive a significant return if the company is acquired or the shares are sold at a higher valuation, £10,000 is still a considerable amount to pay, particularly if they need to exercise their options before an exit.
By obtaining an EMI valuation, you may be able to agree a lower market value with HMRC, making the options more accessible and rewarding for employees.
3. You could miss out on valuable tax planning opportunities
One of the key benefits of an EMI Option Scheme is its favourable tax treatment, provided the relevant eligibility requirements and conditions are satisfied.
An EMI valuation establishes the market value of the shares at the time of grant, including:
- Actual Market Value (AMV): The market value of the shares taking into account any restrictions attached to them.
- Unrestricted Market Value (UMV): The market value of the shares without those restrictions.
Generally, if qualifying EMI options are granted with an exercise price at least equal to the AMV at the date of grant, employees should not be subject to Income Tax on exercise, provided the relevant conditions are met.
Instead, any increase in value may be subject to Capital Gains Tax when the shares are eventually sold. Employees may also qualify for Business Asset Disposal Relief, subject to the applicable eligibility criteria and tax rates.
An HMRC agreed EMI valuation can therefore provide greater certainty and help you structure your option grants more tax efficiently.
For further information, see our step-by-step guide to your EMI valuation.
What if your company hasn't raised investment?
If your company hasn't raised investment or doesn't have a recent, relevant arm's length share transaction, don't worry! You can still obtain an EMI valuation using an alternative financials based methodology.
Rather than relying on a previous funding round's price per share, this approach uses your company's financial performance, including turnover, gross profit and EBITDA, to determine an appropriate valuation.
Our Options team can guide you through the process and help you understand which methodology is most suitable for your company's circumstances.
How to set up your EMI Option Scheme and valuation on SeedLegalsBefore you get started: Check your cap table
Before creating your EMI Option Scheme, it's important to ensure your cap table on SeedLegals is accurate and up to date.
Your cap table should reflect all completed funding rounds, share issuances, transfers and relevant share classes.
This is particularly important as the transactions recorded on your cap table will help determine which valuation methodology is available in your EMI valuation application.
If you need help updating your cap table, see our guide to setting up and editing your Cap Table.
Step 1: Create your option pool
An option pool represents the number of shares your company has set aside for granting options to employees and other eligible recipients.
From your SeedLegals dashboard, navigate to the Options section and select the option to create a new option pool.
You'll be presented with two options.
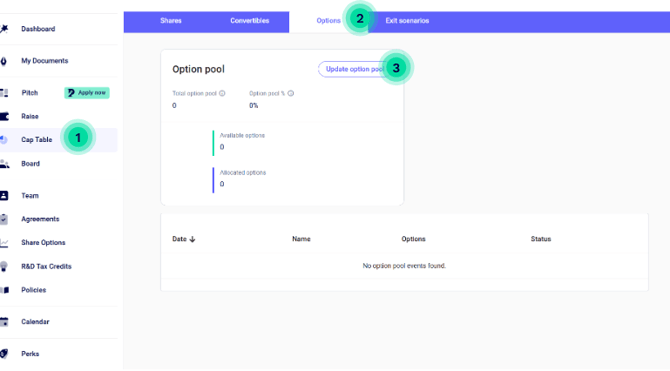
Option 1: Create option pool and approval documents
Select this if your company has not yet obtained the necessary approvals to establish its option pool.
SeedLegals will help you prepare the relevant approval documents, including board and shareholder resolutions, along with investor consents where required.
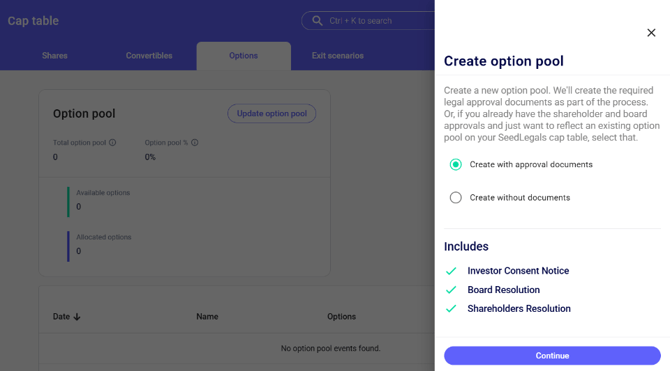
Option 2: Just create an option pool
Select this if your company has already obtained the necessary approvals and you simply need to reflect the existing pool on SeedLegals.
You'll be asked to enter the number of options the company is authorised to grant and the date on which the relevant authority was obtained.
For more information, see our step-by-step guide to creating an Option Pool.
Step 2: Create your EMI Option Scheme
Once your option pool has been created, the next step is to set up your EMI Option Scheme.
Navigate to the Options section of your SeedLegals dashboard and select the option to create a new EMI scheme.
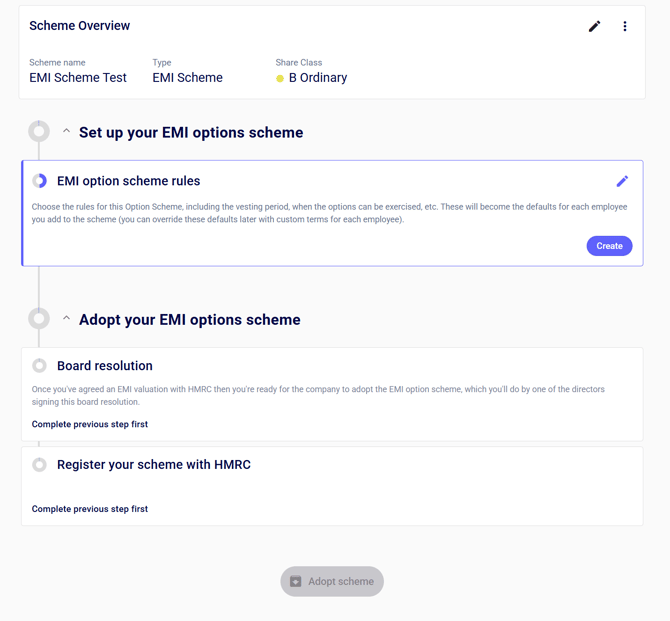
For a full walkthrough, see our step-by-step guide to setting up your EMI Option Scheme.
Choose the appropriate share class
You'll need to select the share class that employees will receive when exercising their options.
Many companies choose to grant options over B Ordinary (Non-Voting) shares, as these can allow employees to benefit economically from the company's growth without receiving voting rights.
However, the appropriate share class will depend on your company's structure and requirements.
If you need to create a new share class, select Add new share class from the dropdown menu and choose the relevant employee share class.
Please bear in mind that any new share class will need to be properly reflected in your company's Articles of Association, with the necessary approvals obtained.
SeedLegals can help you prepare the relevant documentation through the share class creation workflow.
You can follow our step-by-step guide to creating a new share class and the relevant approval documents.
Set your scheme rules
Once you've selected your share class, click Set Details to configure your scheme.
This is where you'll establish the key terms governing your option grants, including the vesting conditions, exercise provisions and leaver rules.
We recommend reviewing these details carefully before proceeding. You can return to amend the scheme details before the scheme rules are formally adopted.
If you're unsure which scheme structure is most appropriate, see our guide to choosing the right Share Option Scheme.
For more detailed guidance on the individual rules, including vesting schedules and exercise conditions, see our Guide to Option Scheme Rules.
Once you're happy with the details, click Create.
Step 3: Complete your EMI valuation application
Next, you'll need to complete your EMI valuation application.
From the EMI Valuations section of your SeedLegals dashboard:
- Select New Valuation to begin a new application, or Continue if you've already started one.
- Navigate to Company details and share transactions.
- Click Set Details to begin completing the required information.
You can also follow our step-by-step guide to completing your EMI valuation.
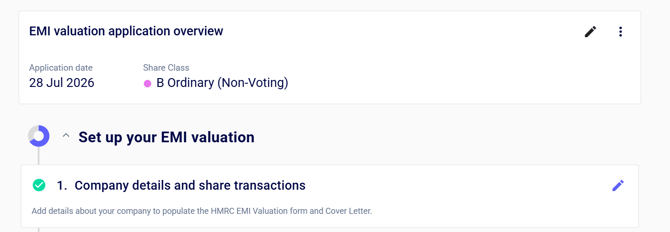
Part A: Company and contact details
Start by entering the relevant information about your company.
This includes a description of your business, its activities, the challenges it faces and the background of its founders.
HMRC uses this information to better understand your company and the context of your proposed valuation.
You'll also need to provide the email address and telephone number of a company director.
SCEC reference number: If you don't know your SCEC reference number or haven't been issued one, you can leave this field blank. This reference may appear on previous HMRC correspondence relating to Advance Assurance or compliance applications.
Remember to click Next to save your answers.
Part B: Share transactions
This section provides HMRC with details of your company's shareholding history and relevant transactions.
Make sure you accurately disclose relevant share allotments, transfers, dividends and any upcoming transactions or developments that could affect your company's valuation.
Once you've completed the required information, click Done.
Step 4: Build your valuation
Next, return to the valuation overview and select Set Details under Build your valuation.
Depending on your company's circumstances and the transactions recorded on your cap table, you'll generally complete one of two valuation methodologies.
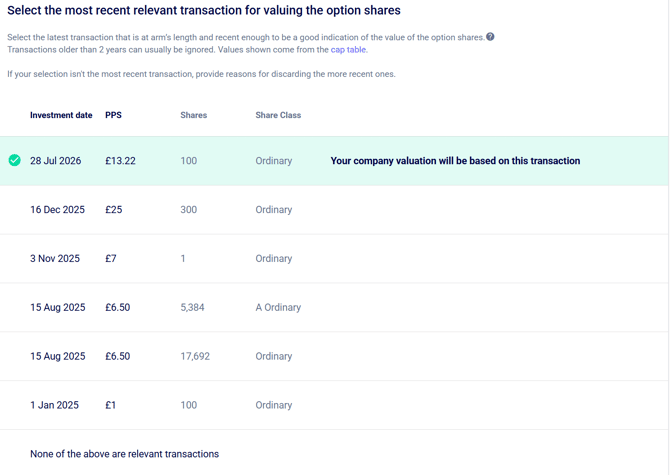
Option 1: Comparable transaction methodology
If your cap table contains a relevant arm's length share transaction above nominal value, you may be able to use that transaction as the basis for your valuation.
In most cases, this will be a recent funding round.
You'll be asked to select the relevant transaction from the available options.
If several transactions took place on the same date involving different share classes, it's important to select the transaction that is most comparable to the share class underlying your EMI options.
If you select an older transaction, you may need to explain why it remains appropriate.
Applying valuation discounts
Once you've selected your comparable transaction, you'll be able to consider any applicable valuation discounts.
These may reflect differences between the shares issued to investors and those underlying your EMI options, as well as other relevant company circumstances.
Select the discounts that apply to your company and provide supporting explanations wherever possible.
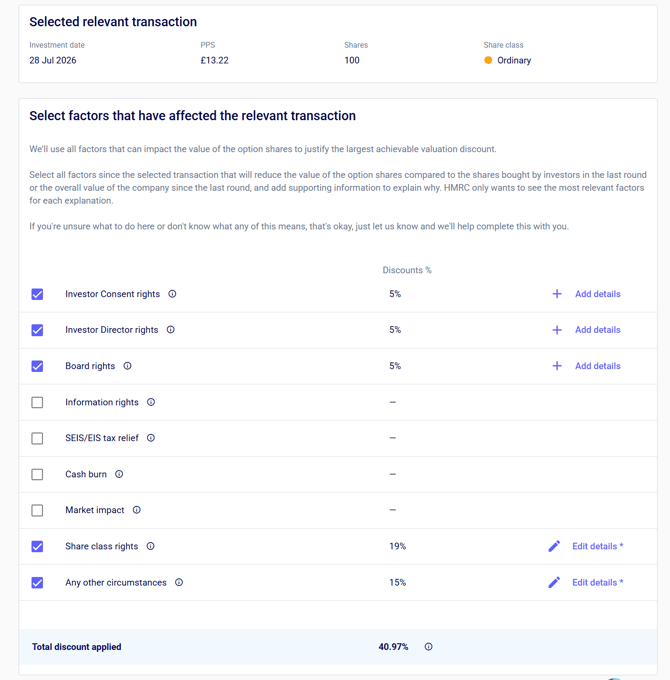
You can hover over the information icon next to each discount for additional guidance.
For certain discounts, SeedLegals will provide an indicative percentage. For others, you'll need to propose a percentage based on your company's circumstances.
Don't worry if you're unsure about the exact figures. Our Options team can review the application and provide feedback on the discounts and supporting rationale before submission.
Important: Any discounts applied should be reasonable and supported by the information provided in your application. HMRC may challenge discounts that it considers insufficiently justified.
Option 2: Financials based methodology
If your company hasn't raised investment or doesn't have a suitable recent arm's length share transaction, you can use the alternative financials based methodology.
Rather than relying on a previous price per share, this approach uses your company's financial performance to calculate an appropriate valuation.
You'll be asked to provide financial information covering up to three years, including:
- Turnover: Your company's total revenue.
- Gross profit: Your revenue after deducting the direct costs of generating that revenue.
- EBITDA: Your earnings before interest, tax, depreciation and amortisation.
You'll also need to provide supporting financial accounts and your most recent balance sheet.
Generally, the latest financial information should be sufficiently recent, with accounts no older than nine months at the time of the application.
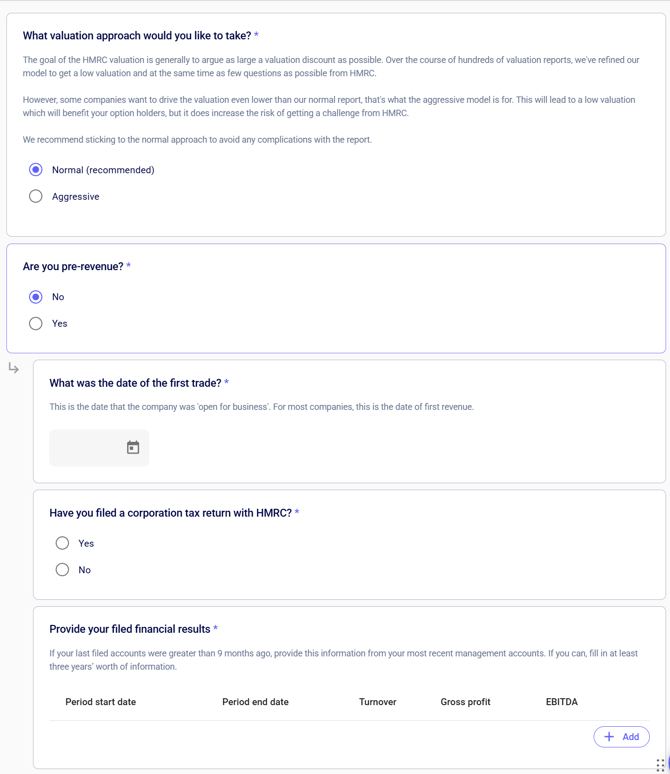
Make sure the figures are consistent with your supporting accounts and financial statements.
Once you've completed the required information, click Done.
Step 5: Enter your proposed exercise price
After building your valuation, you'll return to the valuation overview.
You'll now need to confirm the exercise price that employees will pay to acquire their shares.
We generally recommend setting the exercise price at the Actual Market Value (AMV) agreed with HMRC.
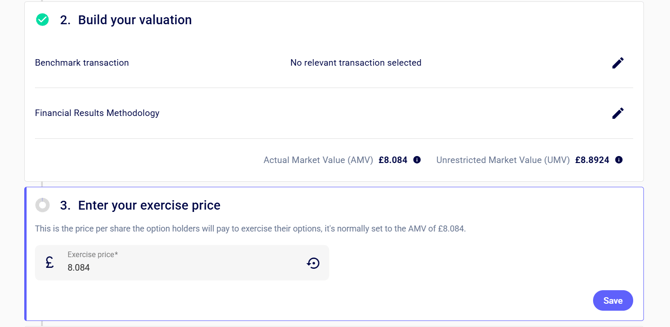
For qualifying EMI options, setting the exercise price at or above the AMV at grant will generally help avoid an Income Tax charge on exercise, provided the relevant requirements are satisfied.
You can choose a lower exercise price, but this may create an Income Tax liability on exercise.
If you intend to use your last funding round's PPS as the exercise price, make sure you've considered the financial implications for your employees.
To enter your proposed exercise price:
- Click Enter Price.
- Review the pre-populated AMV.
- Adjust the exercise price if appropriate.
- Click the check mark to confirm.
Step 6: Submit your valuation for review
Before sending your application to HMRC, we recommend having it reviewed by the SeedLegals Options team.
To do this, select Review My Application.
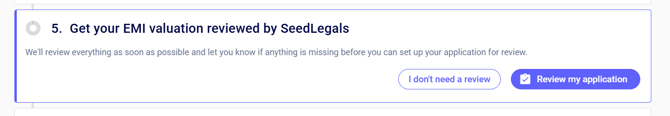
Your application will be sent to our team, who can review the information provided and let you know if any changes or additional supporting documents are required.
Once the review is complete and any outstanding points have been addressed, you can proceed with finalising the application and preparing your submission to HMRC.
Sending your application to HMRC
Once your application is ready, you can email the documents to HMRC at:
savexternal.mailbox@hmrc.gov.uk
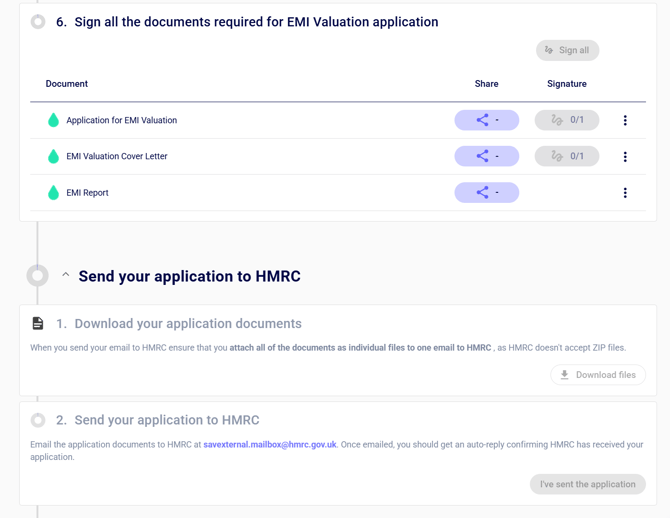
Please also copy emi-options@seedlegals.com into your email so our Options team can stay informed of HMRC's response and support you with any follow-up queries.
HMRC's response times vary, so keep an eye on your inbox in case they request any additional information.
What happens after HMRC agrees your valuation?
Once HMRC has agreed your EMI valuation, you can proceed with granting your options.
An HMRC agreed EMI valuation is generally valid for 90 days from the date of agreement, provided no significant event occurs that could affect the company's value.
What counts as a significant event?
A significant event is a development that could materially affect your company's valuation after HMRC has agreed it.
Examples of significant events can include:
- Changes to your company's share or loan capital.
- A new funding round or significant investment.
- Arm's length transactions involving the company's shares.
- Preparations for a company sale, takeover or flotation.
- The publication of new financial information, including annual accounts or interim financial statements.
You can find further information and examples in HMRC's guidance on significant events.
Why does this matter?
It's important to grant your options within the 90-day validity period.
If a significant event occurs before your options are granted, your previously agreed valuation may no longer be valid, even if you're still within the original 90-day window.
In these circumstances, you may need to submit a fresh EMI valuation application to HMRC before proceeding with your grants.
We therefore recommend considering any upcoming fundraising activities, share transactions or significant company developments when planning your EMI valuation and option grants.
Next steps after HMRC approval
For guidance on the next steps, including finalising your scheme, granting options and registering your scheme with HMRC, see our step-by-step guide to what happens after HMRC approves your valuation.
Once your EMI options have been granted, you'll also need to ensure the relevant HMRC notification and reporting obligations are met.
You can follow our guide to notifying HMRC about the granting of an EMI Option.
Need help?
Our Share Options team is here to support you throughout the process.
Whether you have questions about your valuation methodology, exercise price, option pool or scheme setup, you can get in touch using the chat bubble on your SeedLegals dashboard.
We're happy to help you understand the next steps and make sure you're on the right track!